Being the director of a limited company in the UK is a bit like being the captain of a ship. When the sun is shining and the sea is calm, it’s easy to focus on the horizon, the next big project, that new contract, or expanding your team. But as any seasoned business owner knows, the weather can change in an instant.
If you’re running a small to medium-sized business (SMB), particularly in the fast-paced construction sector, it’s easy to get caught up in the "doing." You’re on-site, you’re managing subcontractors, and you’re ensuring the client is happy. However, your role as a director carries significant legal and financial responsibilities that go far beyond the day-to-day tools.
Taking the time for a "Directors Health Check" isn't just about making sure you’ve paid your VAT on time; it’s about strategic oversight. It’s about knowing that if a storm hits, your business is robust enough to weather it.
In this guide, we’re going to walk through the essential pillars of a financial health check for 2026, from the tech you use to the hidden traps of the Director’s Loan Account.
1. The "Right Now" Check: Real-Time Visibility
The days of handing a box of crumpled receipts to an accountant once a year are long gone. To lead a business effectively in 2026, you need to know exactly where you stand today, not where you were six months ago.
Using the Right Tools
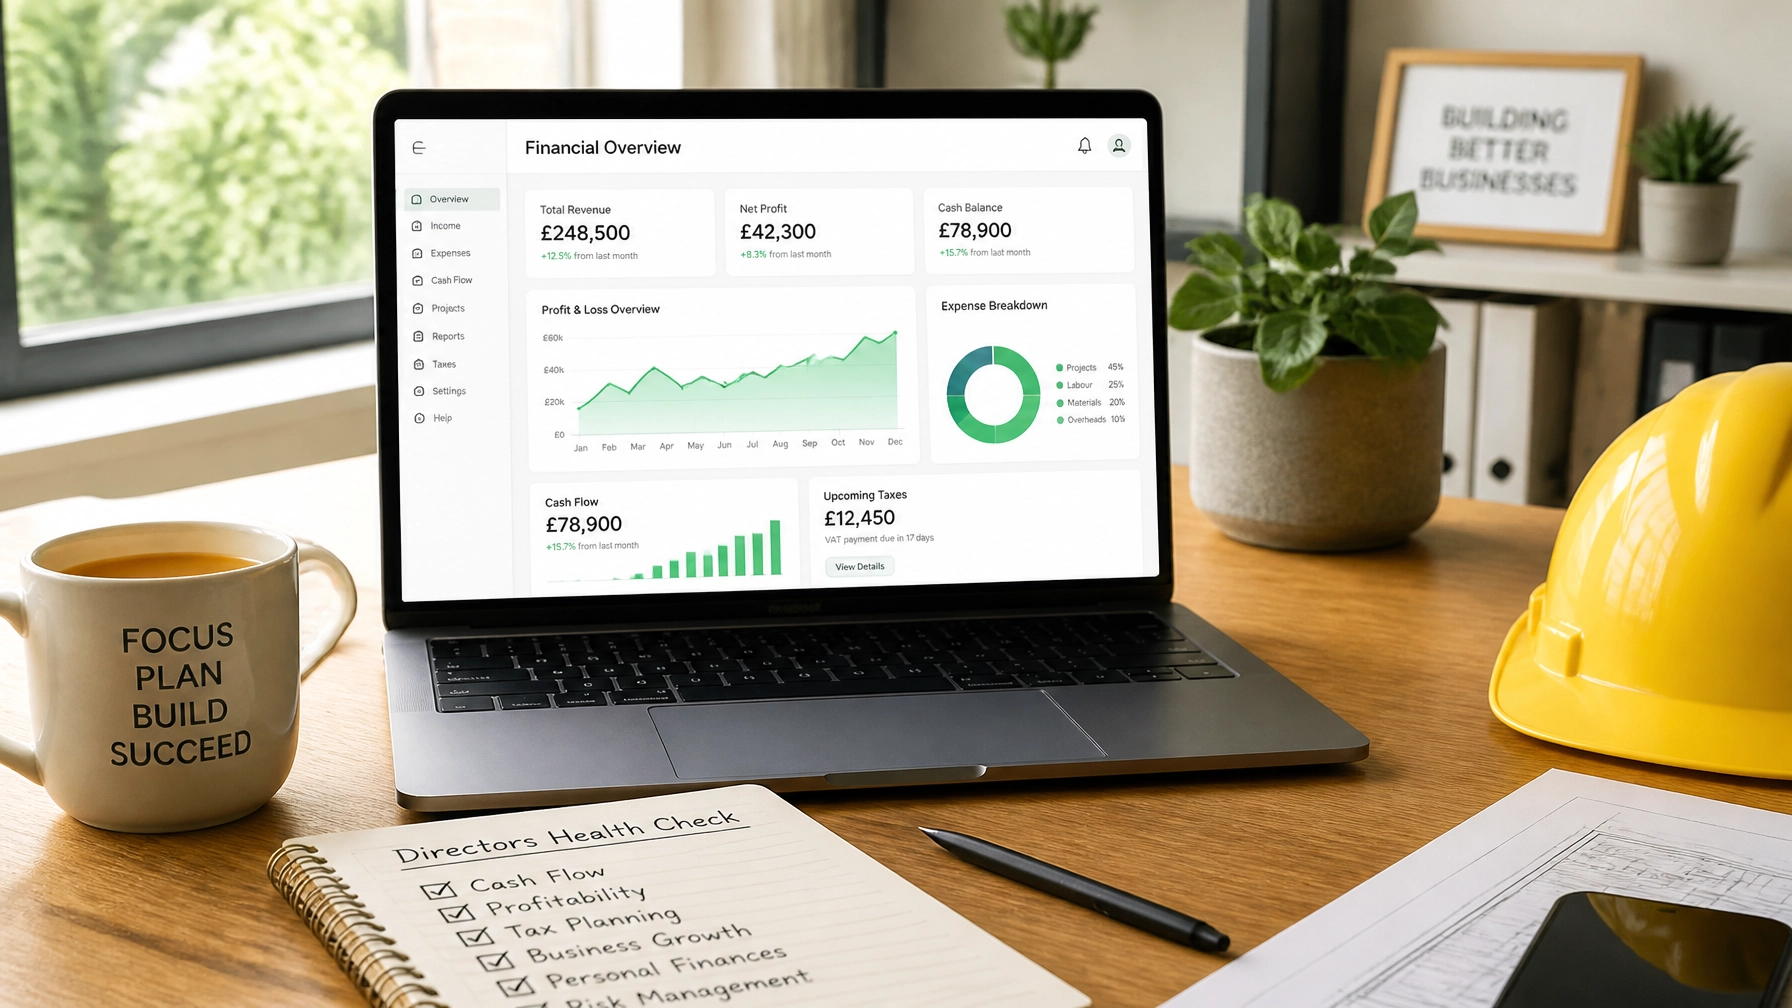
Whether you prefer Xero, Sage, FreeAgent, or QuickBooks, the goal is the same: real-time data. If you aren't logging in at least once a week to look at your dashboard, you’re flying blind.
A healthy director’s routine should include:
- Bank Reconciliations: Are they up to date? If your bank feed is three weeks behind, your "Cash in Bank" figure is a lie.
- Management Accounts: You shouldn't just wait for year-end accounts. Monthly or quarterly management accounts allow you to see trends in your gross profit margins. If a particular type of job is consistently losing you money, you need to know now, not next year.
- Aged Debtors: In construction, cash is king. If your bookkeeping isn't tight, those unpaid invoices can quickly become a terminal problem for your cash flow.
2. The Director’s Loan Account (DLA): The 2026 Shift
This is one of the most common areas where directors trip up. A Director’s Loan Account is, simply put, a record of the money you’ve put into or taken out of the company that isn't salary, dividends, or expenses.

If you take more out than you put in, your DLA becomes "overdrawn." While this is a common way to manage personal finances in a small company, the rules are getting tighter.
The Section 455 Trap
If your DLA is overdrawn at the end of your financial year and you don’t pay it back within nine months and one day, the company has to pay Section 455 tax.
As of April 2026, this rate has seen a significant shift. It’s now aligned with the upper dividend rate at 35.75% (up from 33.75%). That is a huge chunk of cash to hand over to HMRC, even if it is technically "temporary" until you repay the loan.
Health Check Tip: Monitor your DLA monthly. If you’re using it as a "personal piggy bank," you could be hit with a Benefit-in-Kind (BIK) charge if the balance exceeds £10,000 at any point. Our expert payroll management can help ensure your salary and dividends are balanced correctly to avoid these nasty surprises.
3. Liquidity and the "Sleep at Night" Fund
A business can be profitable on paper but still go bust because it runs out of cash. This is especially true for contractors and subcontractors who often face long payment terms or staggered project milestones.
The 3-Month Rule
A healthy business should aim to keep a cash reserve of at least 3 to 6 months of operating expenses. This is your "Sleep at Night" fund. It covers your overheads, your staff payroll, and your own drawings if a major project is delayed or a client goes into liquidation.
Forecasting, Not Guessing
Don't just look at what you have; look at what's coming. Use the forecasting tools within Xero or Sage to map out your next 90 days. If you see a dip coming in two months' time, you can act now, perhaps by chasing up those CIS deductions or negotiating better terms with a supplier.
4. Statutory Duties: Staying Out of Hot Water
As a director, you have a legal duty to act in the best interests of the company and its creditors. This sounds formal, but it has very practical implications.

The Insolvency Test
Every time you take a dividend or a loan, you are effectively declaring that the company is solvent. You should regularly perform two simple tests:
- The Cash Flow Test: Can the company pay its debts as they fall due?
- The Balance Sheet Test: Do the company’s assets outweigh its liabilities (including future tax bills)?
If the answer to either is "no" or "maybe," you must stop taking discretionary drawings immediately. In the world of UK SME management, ignorance is not a legal defence. Having a professional AAT Licensed Bookkeeping Practitioner in your corner ensures that your records are accurate enough to make these calls with confidence.
5. Strategic Growth vs. Just Ticking Boxes
A true health check isn't just about avoiding penalties; it’s about finding opportunities. When we look at a director's finances, we're looking for ways to make the business leaner and more profitable.
- Margin Analysis: Are your materials costs creeping up? With inflation and supply chain shifts in the construction industry, a 10% increase in timber or steel costs can wipe out your profit if you haven't adjusted your quotes.
- Software Optimisation: Are you paying for "add-ons" in your software that you don't use? Or, more importantly, are you still doing things manually that FreeAgent or Sage could do in seconds?
- The Power of 'No': Sometimes, the healthiest thing a director can do is turn down work. If the data shows that a specific type of contract consistently results in late payments and low margins, your "health check" tells you to walk away.
6. How SBS Essex Handles the Heavy Lifting
We know that as a business owner, you didn't start your company because you loved spreadsheets. You started it because you’re great at what you do: whether that’s building, plumbing, electrics, or professional services.

At SBS Essex Ltd, we act as the "Financial Health Department" for directors across the UK. With over 20 years of experience, we don't just "do the books"; we provide the strategic oversight you need to stay compliant and profitable.
From managing complex CIS verifications to ensuring your Xero or Sage accounts are crystal clear, we provide the peace of mind that allows you to focus on the horizon.
Your 2026 Checklist:
- Review your DLA: Is it overdrawn? What’s the plan for the new 35.75% tax rate?
- Check your Reserves: Do you have that 3-month buffer?
- Update your Tech: Are you getting real-time data or working off last month's guesses?
- Verify your Compliance: Are your PAYE, CIS, and VAT submissions morally and ethically on point?
If you’re not sure about any of the above, don’t wait for a letter from HMRC or Companies House. Let’s sit down (virtually or in person) and run a proper diagnostic on your business.
Ready to get your business in peak condition? We offer a free 1-hour discovery consultation for UK business owners. Let’s make sure your ship is ready for whatever the 2026 economy throws your way.
Contact Claire and the team at SBS Essex today.